Quick reads.
If you sent a reply to my last newsletter, I didn’t see it. Technology malfunction. That should be corrected now. Thanks to B. Golden for alerting me to the issue!
Today’s newsletter is not a quick read. Think about how long it took me to write it!! You can’t learn what I have learned in 50 years of doing this in three paragraphs. I guess that supports the saying, “You can’t get rich quick.” Pace yourself. Enjoy the ride (read).
Randy’s Financial Plan of a Lifetime – 2026!
Please…don’t be offended. You’ve been warned.
First time and probably the last.
For the first time, I’m going to talk about taxes, charities, politics, and religion in my newsletter. People have asked me from time to time where I stand on these topics.
As with all the subjects I cover with my financial strategies, my comments on these topics are simply my own opinions. I’m not looking for your agreement with my thinking on these four topics. However, on the financial strategies, I would be shocked if you didn’t agree!
Taxes.
I don’t bitch and moan.
I never complain about taxes. No one who knows me has ever heard me complain about taxes.
I am not one of those people who bemoan the fact that some poor people get a thousand bucks a month from the government, and they don’t do anything to deserve it. For me, that’s like calling the kettle black.
Did I deserve this?
Did I do anything special to get the government to give me about $700/month in tax rebates on my mortgage? As a matter of fact, I was motivated to GET a big mortgage because I knew the government would pay for almost 20% of it.
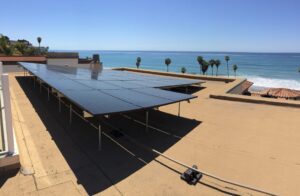
Did I do anything special to get Uncle Sam to pay for $12,000 of my solar installation? Nope. Those solar panels save us $6,000/year in electricity costs, and they paid for themselves in just 4.4 years.

I bought my first Tesla automobile in late 2019. The federal government gave me TWO $7,500 tax credits ($15,000 total). I helped someone else buy a Tesla!
No, I am not.
So, am I going to complain about some less fortunate poor soul getting a few bucks each month to put something in the fridge? Nope. I got and get all of those tax savings because I’m smart enough to game the system.
Robin Hood…sort of.
I see taxes as wealth redistribution. Wealthier people generally pay more taxes than poor people. I actually think that’s a good thing.
When poor people can get some assistance from the government, they’re less likely to fall into dire straits. People who aren’t on the brink are less likely to take things they don’t have from others. Poor people steal and commit more crimes than wealthier people. I see taxes as a necessary evil to keep people from taking my stuff.
Of course, I try to pay as few taxes as legally possible. I used to have an accountant who told me that I was the only non-engineer (I was a sales guy) who created the entire IRS 1040 form in a spreadsheet. I took that as a compliment. It’s not that I cared about taxes all that much. I just like creating spreadsheets!
To me, this is important!
You will never see taxes dictating my life’s plans. Sometimes I might want to spend 30,000 more than usual. Doing that through an IRA withdrawal might put me in a higher tax bracket. I’d pay a little more in taxes because of that decision; I couldn’t care less. I’ll pay the government $3,000 extra if it means enjoying $30,000.
Charity.
Charities. I don’t like charities. There, I’ve said it, and I can’t take it back.
I don’t care if the charity tells me it has no administrative fees and every dollar it collects goes to support its cause. Even then, that charity will still have a Christmas party. Their executives will still fly all over the country to raise money and stay in expensive, exclusive hotels. I don’t want my charitable contributions paying for any of that stuff.
Charity begins at home.
However, I do believe in the idea that “Charity begins at home.“ If I see that a relative or friend can benefit from my giving them funds, I’m all for that. I would rather give my kids, family members, and friends $5,000 than a charity $500.
The Salvation Army would be my only exception to this policy. When I was a young kid, the SA housed and sponsored the Biddy basketball league, where I started playing competitive basketball in the second grade. That program really helped me. I’ve given those folks some relatively small donations.
I want to see these folks get my money.
We give our kids money and advantages whenever we can. Lately, I have been supporting a woman’s English education who served as my tour guide in Angola. English is her ticket to escaping Angola.
I would rather meet a server at the Waffle House and give her a $50 or $100 tip if I thought she needed it and deserved it. When I give money, I want to know it is going to the individual, not to some bureaucratic, despite how noble they want to make it sound, charitable organization.
Politics.
My feelings about politics will definitely piss some folks off!
I don’t care about politics. More importantly, I don’t care about your political leanings. I really, really don’t. I feel so strongly about this that I won’t tell you about my political preferences because that would give you license to tell me about your political ideas…and I don’t want to hear it.
I make my own success. The president has nothing to do with it.
I am responsible for my own success. If someone asked me, am I better off than I was four years ago, eight years ago, or 24 years ago, my answer is always yes. Why is that my answer? Because I follow Randy’s Financial Plan of a Lifetime and the Ten Commandments as best I can.
Every political cycle, politicians campaign on “change.” They tell the public the last guy was a schmuck, and they are going to make things better. That happens with EVERY cycle.
Just plain stupid.
I think it is beyond farcical for someone to rely on the government and the politicians who run it to improve their life. Will my situation four years from now be better simply because of what a politician did? Nope. I don’t think so.
You will never hear me complain about the government. You will never hear me share my feelings about politics and political leaders unless you are in my inner circle, and even then, rarely.
Here’s what I really think about politics.
I don’t share my political views for one simple reason. The person who asks me about my political thinking isn’t interested in what I have to say. They just want to tell me what THEY think about politics.
I don’t share my feelings about politics because I don’t want to listen to someone else’s. Most people, when talking about politics, couldn’t care less what my views are; they just want to tell me theirs.
I will actually go out of my way to avoid these kinds of people. People think they are political science experts because they listen to a guy on the radio or TV and simply repeat what they heard. I will walk the other way as fast as I can when I think someone is about to explain to me how they think about politics.
It don’t matter one bit.
To me, it doesn’t matter if you’re conservative or liberal. Just that comment alone will drive some people who read it bonkers. They think it implies I don’t support their political side.
I think both extremes suck. It’s especially appalling when a conservative or a liberal doesn’t just accept the fact that you might not agree with them. Their attitude is frequently, “If you’re not with me, then you’re against me.” That’s one of my biggest pet peeves.

Six to four wins it.
I also find the presidential elections beyond comical. We have more than 300 million people in the United States.
However, five or six “swing” states will decide the election. California is never going to vote Republican (although more Republicans vote in California than in any other state), and Wyoming is never going to vote Democratic.
In those five or six swing states, about 40% of voters are Republicans and about 40% are Democrats. That leaves the 20% in the middle who are “undecided.” Only about 50% of people vote, so the 10% of undecided voters, down from 20% available in just five or six states, will decide the election for more than 300 million people. So, if one party can win that 10% of undecided by a margin of 6-4…in five or six states, they win. That sounds dumb to me.
Religion.
I believe in God. I couldn’t care less what religion my friends practice or if they practice religion. Why? Because it wasn’t my day to watch them. Anyone’s religion is their choice, and just like in politics, I’m not here to try to change someone’s mind.
What did you learn?
After reading this, I doubt you know whether I’m a Republican, a Democrat, or an Independent. I don’t think you know what religion I practice. You probably do know that I don’t concern myself with taxes. I don’t let taxes run my life. I pay what I owe.
Finally, you now know I don’t like formal charities, but I absolutely love giving money to people whom I know or people who need it, as long as they are making their own contribution to themselves and/or society. There’s no free lunch unless you practice credit card arbitrage.
So that’s it. Don’t write me on any of these topics with a plan to move me to your “side.” I won’t like it if you try that.
Now, are you ready to talk about money?
My newsletter tagline reads:
THE FINANCE, TRAVEL, TRACKCHASING, AND LIFE ON THE ROAD NEWSLETTER.
This newsletter is about finance!
Randy’s Financial Plan of a Lifetime – 2026.
24 years. Retire. Invest. Spend. This is how I did it. And, maybe more importantly, how I’m doing it.
My most important and popular post of the year.
I have not earned a single dime.
I’m in my 25th year of retirement. During that time, I have not earned a single dime of work income. When I retired, I never wished I were still working. Never.
I often want to ask people, “Where would you be if you had not earned any money whatsoever during the past 25 years?” I want to ask that, but I don’t.
My plan.
This is MY financial plan. I took the best ideas I could find, mixed them, and matched them to make MY plan. I rarely come up with any of my own ideas. However, I am very adept at taking other people’s ideas and turning them into my own plan.
I have been very successful in retirement. How do I define success? From a monetary point of view, I only wanted to achieve two things.
- Provide for my wife and children.
- Afford a lifestyle that lets me travel the world constantly without financial worry.
I am happy to report that my Financial Plan of a Lifetime has allowed me to achieve both of these monetary retirement goals.
24 years of financial results.
I have completed 24 years of retirement. It went fast! This is my 24th annual review of my retirement financial plan. According to my net worth statement, I have more money today than I did 24 years ago. Later, I will explain why the previous statement indicates a major flaw in my retirement plan.
I’ve been telling people about my plan every year for 24 years now. Much of what I share in 2026 is the same as what I shared in 2025 and for the years before that. Why is that?
I’ve had a good plan from the beginning! I’ve made some minor tweaks, but only minor tweaks. However, when I tell you how I did it, I’m reinforcing to myself why my Financial Plan of a Lifetime is such a good one.
Please don’t mistake my confidence for bragging. To put it simply, I am sharing PEARLS with you. All you have to do is bend over to pick them up.
Most people.
I think most people would like to retire early. Most people would like to never have to worry about money. I think most people would like to travel the world without worrying about how they’ll pay for things.
If that is you, then, and this is most important, you will have to put these pearls into your own piece of jewelry. Look for the “Pearl” designation throughout my post in RED.
No matter what your age, this plan works.
If you are in your 20s or 30s, you might think, “This is just some old guy trying to brag about how he planned for retirement. That doesn’t have much to do with my world. I won’t be retiring for decades. I don’t need to give this topic much thought right now.”
If you are in your 40s or 50s, you might say, “Hold on. I haven’t been giving these financial reviews all that much attention. But now, just over the horizon, I can see retirement. Maybe I should pay more attention to how Randy did it.”
If you are in your 60s or older, you have likely initiated your financial plan….or not. If so, you can compare your thoughts on retirement financial planning to how I did it. Maybe you didn’t have a plan? Surprise! You DID have a plan all along. What was your plan? No plan!
People don’t change.
After having been a sales manager for years, I learned a few things. One was “People don’t change.” I don’t know if they can’t change or won’t change, but few people do change.
I know this. When I wanted to change something in my life, I went to an expert, someone better than I was in the area I wanted to improve.
Always improving.
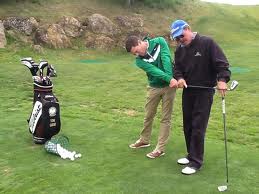
When I was 45, I wanted to improve at golf. I was a 25-30 handicapper. If you don’t know anything about golf, I was really bad.
My goal was to become a “single-digit” handicap by the time I turned fifty. I figured I would have a lot more fun in retirement playing golf if I were more likely to break 80 than 110.
I estimate I took more than 300 golf lessons. I became a single-digit golfer. I once shot a 68 on a course with a 135 slope rating. Just so you know, I putt everything out. My lowest ever golf index was a 3.2. I took lessons from a golf pro (several pros) because the guy, and some women as well, could play golf better than I could.
Here’s the pearl.
Find people who are better at something you want to be better at and do what they tell you. That is oh so simple, but few people can or want to do that.
My most popular newsletter.
This is my most popular newsletter of the year. I think people just want to look over my shoulder so they can read my bank account balance. I wish everyone were more interested in changing something about their financial plan so they could achieve the same results I have gotten.
I get the most reader responses and questions from this post. I hope you enjoy it.
People have deep-seated feelings about money.
Based on what we all learned when we were five years old, everyone thinks about money differently. Few people can change how they feel about money, even if they don’t know how to manage money at all. Not being able to change is a bit sad, but it is a reality in so many cases.
It seems a bit weird to me that how we feel about money is something we learned as small children. That’s what I’ve taken from everything I’ve read. It seems even more bizarre to me that people who don’t understand money wouldn’t take a plan like mine, or at least SOMEBODY’S
plan, and run with it! I’m thinking that most people don’t understand that they don’t really understand how to manage money.
This situation is similar to asking whether people are above-average drivers. About 75% say they are above average. Of course, we all know that can’t be true. Most people are not above average with money either.
This is how I did it.
There’s an excellent chance you think about money differently than I do. That’s OK. I’m just sharing, as candidly as possible, exactly how I did it. I hope you find what I have to share entertaining. Maybe you’ll find what I have to share educational. Perhaps what I share is so counter to your thoughts on money that you will have a hard time reading everything posted here.
Not every option is the best option.
Different strokes for different folks? No, I don’t believe in that. Some things in life, if done the best way, yield significantly different and, most importantly, better results.

R
I was born in 1949. We were poor. Luckily, we didn’t KNOW we were poor. That made being poor easier!
The year 1949 was a long time ago. Heck, 2002, when I retired, was a long time ago. In 1949, cars didn’t have air-conditioning, power windows, or self-driving capability. Even AM radios were an option in 1949. In 2002, there were no Teslas, iPhones, YouTube, or Facebook. 2002 was about as long ago as 1949!
Why did I retire?
I retired at 52. I wanted to retire much earlier, but things got in the way.
Why did I retire? I was the kind of guy who liked to play more than work. I wanted to do a good job when I worked, and I did. As I thought about retiring, this thought was at the front of my mind. “If, out of the infinite number of things I could do with my time, working for Procter & Gamble was #1, then I should not retire. However, if I had the money and didn’t need to work, I might as well spend my time doing exactly what I wanted, and working for a big company wasn’t that.”
I always means we…and it’s just shorter to write.
You will often hear me use the word “I” in this message. I don’t want you to get the wrong impression. Some time ago, I married a beautiful young blonde girl named Carol. Carol and I did all of this together.
I tend to use “I” when describing my retirement financial plan because I am the money man in our household. Carol is the “everything else” woman.
What does that mean? I handle the financial strategy. Carol pays the bills. Carol handles everything else in our household. She does everything!
I’m not lazy, just focused.
I’ve told you that I don’t do any chores at home. I last mowed a blade of grass in 1983. I will never mow another blade of grass in my life. That’s a promise. I don’t wash dishes or clothes. I don’t know what day the trash man comes or when the cleaning lady is scheduled to show up. I don’t worry about knowing anything that I don’t NEED to know.
It is essential for the reader not to take anything that I say out of context. I am not some chauvinist unwilling to support how a typical household must be run.
I am simply unqualified. Unqualified people should not attempt tasks for which they are incompetent.
The infamous job jar.
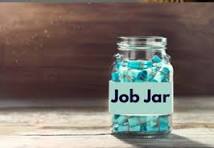
Carol has attempted to involve me in the household chores and responsibilities. She even created a “job jar.” This girl doesn’t give up! The job jar contained a list of chores. She neatly arranged small papers, just like you might find in a Chinese fortune cookie.
Carol explained to me, as if she were a kindergarten teacher, that the job jar was for me to reach in and grab one of the small papers. I should read my assignment and then complete the task. As I expected, this didn’t work well.
In an effort to be a good husband, I would reach into the jar and grab one of the “opportunities.” However, I couldn’t resist telling Carol that I didn’t want to do what was described. As a loyal husband, I had to stick up for myself.
Once in a while, I tried to do a chore.
Occasionally, I would find something I thought I could do in the job jar and attempt to do that chore. Carol would look over my shoulder and soon tell me my actions didn’t meet her standards. She would then redo what I had done to ensure the result met her standards.
As you might understand, this was frustrating for me. Why would I waste my time doing a chore or handling a household responsibility if Carol was going to come right behind me and redo it? This is how we ended up in the position we have been in for decades. I don’t do anything except handle the financial strategy.
No, I don’t.
The reader might ask themselves, “Randy, do you do this or do you do that?” Folks, I don’t do anything. I’m not bragging. I’m simply telling you how it is. So, with that as background, I say to you that I am fully responsible for our retirement financial plan. Carol agrees. She does not look over my shoulder regarding our financial retirement plan and try to redo my financial strategy. She is an intelligent woman. She knows that, just like with Allstate, she is in good hands.
When I quit…I quit.
I have never worked for anybody else in retirement or earned a single dime of work income in more than 24 years. I don’t need to work, and more importantly, I don’t want to work for money. Some folks say they love their jobs. I would love to hear what those people would say if their job stopped paying them money.
Let’s consider this. When I decided to retire in 2002, I had a certain amount of money. Now, I have quite a bit more than I had in 2002.
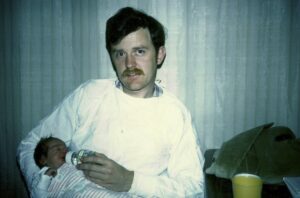
How did I get in this position?
How in the world did that happen? I haven’t worked in retirement. We still haven’t received any money from anyone else to build this growing net worth. Carol never worked outside the home for money or any other reason after our daughter Kristy was born (above!). To avoid revealing Kristy’s age, I’ll say Carol hasn’t worked outside the home for money in more than four decades. Don’t get me wrong. What Carol did for our family mattered far more than what I did in business. It’s just that, in our world, what I did produced more income.
You will get the complete “How I did it” story.
In this post, I will tell you precisely what my Financial Plan of a Lifetime was and the results I have achieved so far. However, if you’ve been reading my newsletter for long, you know I always try to provide a little background. As a result, my message isn’t always a short read. Do you expect to learn how to earn hundreds of thousands of dollars by reading three paragraphs?
Nevertheless, so many readers open these messages every couple of weeks, hoping to get a chuckle or a piece of information that might be valuable to them, their family, or their friends. And they do!
How will you react to what I’m sharing?
I always say that everyone can choose their own reaction to whatever they encounter. Everyone can decide whether they want to react positively to the information that comes their way.
What is your reaction when I tell you this? I retired 24 years ago. I’ve been spending like a drunken sailor ever since. I never earned any income whatsoever from work during that time. I have more money now than I did when I retired. What is your reaction to all of that?
In my judgment, I would find it perfectly acceptable if you concluded, “Randy is a financial stud.”
Others might say, “Randy likes to brag”.
If you had either of these reactions and you were willing to share them with me, this is what I would tell you.
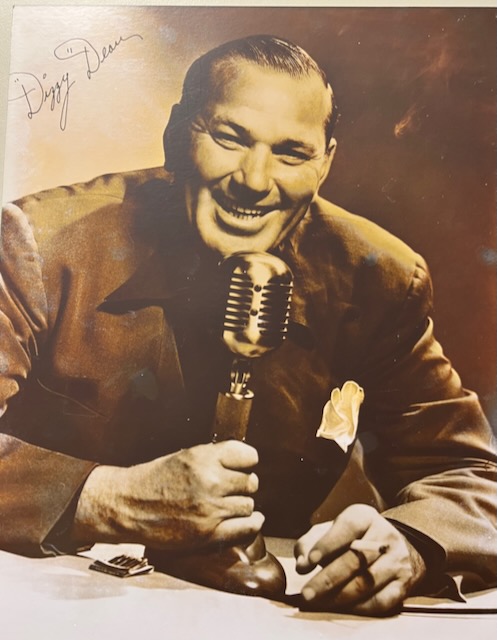
Dizzy Dean had it figured out.
If you are in your 20s, you probably don’t know who Dizzy Dean was. Dizzy Dean was a phenomenal young pitcher from Arkansas who played for the St. Louis Cardinals. He was so good that he is in the Baseball Hall of Fame in Cooperstown, New York.
Later, he became a TV broadcaster for Major League Baseball’s “Game of the Week.” Ol’ Diz was a country boy. He was fond of saying, “It ain’t braggin’ if you did it or you can do it.” I have done precisely what I am telling you I did. I always follow Dizzy Dean’s adage, “It ain’t bragging if you did it.”
You’ve probably heard this before.
You may have heard other people tell you something similar to my story. They might say they retired long ago and have more money today than when they retired. If you know one of those people or you ARE one of these people, you might think that person WAS a financial stud. I will tell you this.
Pearl! It is easy to make this mistake. Don’t do it. Enjoy your money.
I am not bragging; I am NOT a financial stud. Anybody who tells you that they retired a long time ago and have more money today than when they retired has made an enormous mistake. If they don’t realize that, then they have made TWO mistakes.
Pearl. Don’t optimize for the wrong thing.
People in this situation have optimized for money more than they should have. They worked too long or didn’t spend enough in retirement. That’s right. They optimized for money, not personal enjoyment. Money, by itself, isn’t worth anything. If you have more money after a certain number of retirement years than when you retired, in my judgment, you have FAILED!
I have failed…but it’s not too late.
This is not a message about you. It is a message about me. Financially, I have failed in one regard. I’ll bet you didn’t see that coming.
That’s right. When you hear me say that I have more money today than when I retired 24 years ago, don’t think I am bragging or a financial stud. You should think, “Randy is failing.”
Maybe you think Randy cut back on his expenses so much after he quit working that he had no fun. Read on. Decide for yourself.
Pearl. Limiting your spending does not usually optimize for personal enjoyment.
One way someone could achieve what I have done is to severely limit their spending in retirement. I didn’t want to do that. If I retired, I would have a lot of free time. If I had a lot of free time, I would likely need something to entertain myself. Filling my free time would be expensive.
I wanted to spend like a drunken sailor.
My objective in retirement was to spend money like a drunken sailor. Wait! When have you ever read about a retirement financial strategy where the author told you that he or she wanted to spend like a drunken sailor?
I wanted to travel, have nice things, and play golf with the guys down at the club. That’s a much different lifestyle than living in a van down by the river.
At this point, the word “I” really applies to me, not so much to Carol. Carol is not interested in spending like a drunken sailor. She doesn’t even drink that much.
Carol married a world traveler, although she probably didn’t know that when she walked down the aisle.
If Carol weren’t married to me, she might never travel. Believe it or not, she still does her household chores wearing clothes that she wore in college. I am not exaggerating. What does that tell you? First, she don’t eat much. She can still fit into the clothes she wore in college! She works out at the gym several times a week. Carol would be just as happy doing all of her chores at home and never stepping onto an airplane. I don’t roll that way. Because I don’t roll that way, she don’t exactly roll that way either.
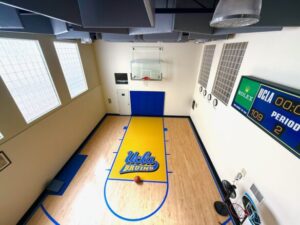
Bigger is better, in my judgment.
When we retired in 2002, we bought a new house. Did we downsize? No, we did not. That’s not my style. I don’t believe in downsizing anything in retirement. I went big. I built an indoor basketball court about the same size as my boyhood home, where I lived for the first 15 years of my life.
Actually, Carol complains that our house is too big. I don’t think anything is “too big.” My advice to her? Close the doors to some rooms and don’t go in them! That instantly makes the house smaller. Her reaction to my advice? Not printable.
Was this house going to be our forever house? Maybe. We paid $1.2 million for it. Think about that for a second. In 2002, we spent more than $1 million on a house. It must’ve been some house, huh? How much is $1.2 million worth in today’s dollars? Dollartimes.com says $ 1.2 million in 2002 is worth well over TWO million in 2026.
What was the first thing we did with the house we bought at the beginning of retirement? We tore it down. That’s right. I guess that house wasn’t our “forever” house, was it?. We could have just changed the wallpaper, but we tore it down. That house caused me to do one of my rare household chores.
I learned to swing a pickax.
I went to Home Depot and bought just one item—a pickaxe. I would go down to the new house with the objective of totally destroying one room a day with my pickaxe. It was fun. It’s not like I enjoy doing chores, but this one wasn’t that bad.
In no time, I had torn down the house to the studs. Then, I discovered the house had about an inch and a half of “light concrete” on all the floors. The bathroom showers and such were built the same way 1950s bomb shelters were. They were all REINFORCED. Concrete and rebar. I needed some help.
Meeting these folks was a trip.
I came across a minister who ran a shelter for people who needed rehab from drugs and alcohol. To this day, I don’t remember how I met this guy. I told the minister he could keep all the wood and anything else of value he found in the house if his guys helped me destroy our million-dollar mansion.
I worked side-by-side with these folks. Did they have the stories to tell? They had been in jail. They had lived on the “wild side of life.” I’ve never even taken a puff of a cigarette. It was entertaining to go down every day and listen to their stories.
We hauled the debris we created in this multi-level structure up to the top level in massive, hard plastic trash cans. Soon, all this debris was so heavy that I was told to remove it before the floor collapsed. I rented a full-sized dump truck and made six trips to the dump in one day, driving that truck at about 30 mph on the San Diego freeway.
The house was now a shell of what it used to be. I hired a guy to do the final demolition. He did that demo in one day. When we negotiated the demolition price, we ended up being $700 apart. I suggested we flip a coin for that final $700. The demo guy agreed. We flipped a coin. I won. He did that demo pretty cheaply. Folks, that’s how I roll.
I tore that house down and built a new one.
When it came time to build the new house, I spent another $1.2 million on its construction. In total, I spent $2.4 million in 2002 on this retirement home (buying the first house, tearing it down, and building a new one).
How much was our total construction cost of $2.4 million worth in today’s dollars? Dollartimes.com says $2.4 million in 2002 is worth more than FOUR million dollars in 2026. Oh yeah, we didn’t sell the house we lived in at the time. Why? We couldn’t. No buyers. That put a little “pucker” into the subject of cash flow.
This was a good idea.
I hired a construction consultant for, as I remember, $80,000. He shared all of his construction knowledge and contacts with me. We ended up with 80 subcontractors, and several of them had subcontractors below them. I’ll call our construction consultant, Matt, because that was his name.
Along the way, we hired a woman to be our “space planner”. She was wonderful. I’ll call our space planner/designer Patty again because that’s her name.
If Matt had been left to his own devices, he would have built a tank. If Patty had been left to her own devices, she would have given us a beautiful butterfly that flew around on an unlimited budget. You can imagine the meetings that Matt, Patty, Carol, and I had in building our forever home.
How many door hinges should a house have?
I call our home our “modest seaside cottage”. What did $1.2 million in construction costs get us in 2002? I think our house has 33 doors. I haven’t been in all the rooms yet. The doors were the best value in the house. They are solid Honduran mahogany. Each door needed three hinges, so we needed nearly 100 door hinges in total.
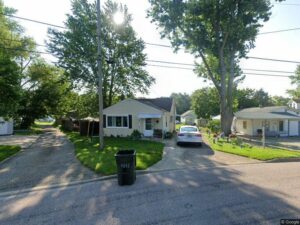
I grew up poor. No problem. I didn’t know we were poor.
I told you I grew up poor. I know you won’t believe this, but I grew up in a small home at 411 Doering in East Peoria, Illinois. I lived in this house until I was fifteen. The house had 990 square feet.
How many doors did that house have? To the very best of my memory, it had three doors. There was the front door, which we never EVER used. We used the back door to enter the house. Finally, a door separated my room from the home’s one bathroom. Three doors. Nine hinges. Times have changed.
The cost estimate for each hinge for our new home ranged from $6 to $24. We had to decide whether to go with the low, medium, or high bid from each subcontractor. It’s rare for me to cheap out. For the door hinges, the contractors made it sound like the six-dollar door hinges would probably rust away in the first five years of occupancy. Then, those solid doors would fall over onto the floor. On the other hand, the $24 hinges were made to sound like they were pure gold. Did we want to spend $600 on hinges or $2,400?
We made decisions like these with all 80 of our subcontractors. Most of the time, we chose the higher bid and better quality over the lower bid. I was practicing spending like a drunken sailor!
Pearl. Ever used cash discounts? Really big cash discounts?
Oh yeah, we used cash discounts extensively. What a huge money saver that was. It was just fun being part of those negotiations. I wish I could tell you more about the winter night when I ventured into a bad part of town with a Hartman briefcase carrying $63,000….in cash, but I can’t. Details on that subject might be forthcoming, but likely not in a future newsletter.
Pearl. We optimized for personal enjoyment.
We spent a lot of money on our house. I also told you that I wanted to travel a lot in retirement. I’ve done that. Carol and I have been to 105 countries. Yes, I played a lot of golf, too.
A friend sent me this note. I thought it made perfect sense. This is what it said.
“Don’t be afraid to spend money on traveling. Be afraid of growing old and realizing that the only place you ever went was to work.”
I’ve been to more than 15 countries, most of them return visits, in 2026 alone. I’m writing this on a plane to Amsterdam.
Pearl. My pre-retirement spreadsheet was my financial bible.
This is really important. I have a spreadsheet for everything. I credit my pre-retirement spreadsheet with letting me pull the pin on retirement. I often think back on what might have happened if I had screwed up a formula in that spreadsheet. That kind of planning helped us achieve financial success.
How much would come in and how much would go out.
The spreadsheet told me roughly how much my investments would earn in retirement. The spreadsheet told me roughly how much my expenses would be in retirement…for the rest of my life.
A trip of a lifetime…every month.
I wanted to travel. I may go overboard on travel. My goal is to take the “trip of a lifetime” every month, and I pretty much do.
I wanted to spend the money I had earned. Having my retirement money sitting in a Vanguard retirement account while I aged, sitting in a La-Z-Boy recliner watching TV, wasn’t part of my retirement plan. I have no idea how long I will live in retirement. I can tell you this. I’ve been busy in the first 24 years of my retirement!
America loves numbers.
The table below shows how many nights I have traveled away from home since retirement.
| TOTAL | 3,898 |
| 2026 (so far)
2025
2024 |
188
228
181 |
| 2023 | 162 |
| 2022 | 181 |
| 2021 | 129 |
| 2020 | 115 |
| 2019 | 166 |
| 2018 | 213 |
| 2017 | 171 |
| 2016 | 186 |
| 2015 | 194 |
| 2014 | 189 |
| 2013 | 186 |
| 2012 | 142 |
| 2011 | 162 |
| 2010 | 159 |
| 2009 | 167 |
| 2008 | 162 |
| 2007 | 146 |
| 2006 | 160 |
| 2005 | 163 |
| 2004 | 143 |
| 2003 | 80 |
As you can see, I have averaged about 170 nights of travel each year for 24 years. In 2018, I spent 213 nights on the road. During 225, I broke my record with 228 overnights. I am a “road warrior”. I like to travel.
What does this REALLY mean?
For each of those travel days, I want you to think about this. On 99% of those nearly 3,900 days, I needed a hotel. On 99% of those days, I needed a rental car. On 99% of those days, I bought two or three meals in a restaurant. About every third or fourth day, I flew on an airplane.
I have parked my car at the Los Angeles International Airport for over 4,000 days during retirement. As you can imagine, we have spent some money on travel.
Remember, I haven’t earned any money from working in retirement for more than 24 years.
It doesn’t cost that much more to go first class, unless you’re on an airplane.
Speaking of spending money, I like driving brand new luxury cars. I was driving new Lexus automobiles when I retired. Seven years ago, I decided that electric cars were the way to go for me. In 2019, I took delivery of my first $100,000 automobile, a Tesla Model X.
What does all of this prove?
I share the above regarding the cost of our housing, travel, and automobiles to prove one point. We didn’t reach our current net worth by skimping on expenses. I literally did spend like a drunken sailor!
Pearl. Now let’s get serious.
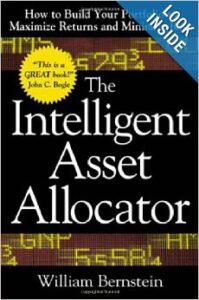
We got there by having a solid financial plan. I started with William J. Bernstein’s book, The Intelligent Asset Allocator: How to Build Your Portfolio to Maximize Returns and Minimize Risk.
I read it, but more importantly, I practiced what the book advocated daily. The author taught me the value of a diversified portfolio of stocks and bonds in retirement and the importance of never trying to time the market. I planned to invest in low-cost index mutual funds. By doing that, I was nearly guaranteed to achieve the market’s average results. I would be able to match the market.
I avoided financial planners (like the plague) who charged a percentage of my assets as their fee. “Being the market” by simply being “average” was good enough to beat 90% of active investors and those who followed the recommendations of financial planners.
Pearl. Make a plan. Stick to the plan. Change the plan only if absolutely necessary.
I have not deviated from my financial plan one iota since 2002. I don’t know if Dizzy Dean said this, but he could have: “If it ain’t broke, don’t waste time fixing it.”
I still have the same eleven Vanguard mutual funds I had when I retired. Nothing else. My plan didn’t have to be done with Vanguard. Other major investment management companies offer similar products.
What were those funds?
| Total Stock Market Index Fund Admiral | VTSAX |
| Total International Stock Index Fund | VTIAX |
| U.S. Growth Fund Admiral Shares | VWUAX |
| Windsor II Fund Admiral | VWNAX |
| Strategic Equity | VSEQX |
| Explorer Fund Admiral | VEXRX |
| Short-Term Investment-Grade Fund Admiral | VFSUX |
| Short-Term Bond Index Fund Admiral | VBIRX |
| Intermediate-Term Investment-Grade Fund Admiral | VFIDX |
| Long-Term Bond Index | VBLAX |
| High-Yield Corporate Fund Admiral | VWEAX |
I mentioned that when I retired, I created a financial spreadsheet. That spreadsheet included just two essential items. It helped me understand my expenses and my expected investment income in retirement.
Pearl. Don’t have a budget? Sorry to hear that.
A household budget has always been a critical first step in my financial planning.
Don’t miss this point.
Some might call their budget a “financial tracking” tool. I do. I use this tool about 20% of the time to look back and about 80% of the time to look forward. Did you get that? I use my time on financial tracking mainly to look ahead!
The year before I retired, I knew how much I was spending in 10-15 different expense categories. My spreadsheet also included another essential element: for each expense category, I made an educated guess about the inflation rate for the next year and every year into the future.
I can tell you how much each of our expenses will be by category within a fairly narrow range in 2030, 2040, and beyond. The challenge will be to live long enough to prove those projections!
I could tell you how much our electric bill will be in the future. Wait. That’s a bad example. We have solar panels, and our electric bill is zero. How about this example? I can tell you how much our gasoline expenses will be in the future. Wait. That’s a bad example. I drive a Tesla, and my gasoline expense AND my cost to charge my car are zero…but you get the point.
A budget for all times…understand the subtleties.
This is my kind of budget. Looking back, a budget is a factual document. Looking forward, a budget is an educated estimate. If a person doesn’t have a budget, they won’t know where they’re at or where they’re going. I once read a book titled “If you don’t know where you’re going, you might end up there”. A budget/financial tracking tool is the basic building block of a sound financial plan.
My budget tells me how much I have spent and, more importantly, how much I expect to spend.
In hindsight, this was a pretty big decision.
When I decided to retire, I needed to look at how much money I had at the start of retirement. I thought I had enough to retire for the rest of my life and never work again. I told my bosses to “take this job and shove it”. Not really, but that does sound kind of cool, huh? What if my future projections had been wrong? Had I been wrong, it’s unlikely you would be reading this newsletter.
Based on my homemade spreadsheet, I submitted my retirement papers and told the folks they could reach me at the beach (that’s not me in the photo!). Yes, we live at the beach.
Pearl. How much would I earn on my investments?
With some historical research, I estimated a reasonable rate of return I could earn on my retirement assets. Of course, those rates of return would be different every year. There would be ups and downs.
I didn’t expect a global financial crisis or a global pandemic during my 24 years of retirement. Stuff like that is hard to predict, but it’s not surprising when it happens. Bumps in the road will always be there.
October 11.
My fiscal year ends every October 11. Why October 11? When I retired on June 30, 2002, it took me until October 11, 2002, to implement my financial plan.
Pearl. This year’s results.
The bottom line!
For my 2025/2026 fiscal year ending October 11, 2025, my retirement portfolio earned 13.01% percent. That’s an excellent result. The annualized ROI for my entire 24 years of investing is now 8.93%. That’s about what should be expected from an almost all-index portfolio of 64% stocks and 36% bonds.
The table below shows my return on investment (ROI) for each of the past 24 years. I use the Modified Dietz method to calculate my ROI. My portfolio has a 64% stock allocation and a 36% bond allocation. There have been only two losing years in my 24 years of investing.
Monday morning quarterback.
I had one guy tell me I would have made a lot more if I hadn’t invested in bonds and had put all my money in stocks. That is true. But the bonds provided some stability during the global financial crisis and when the market cratered temporarily at the beginning of COVID-19.
These are my annual investment results for my entire retirement portfolio by year.
| FY ENDING | ANNUAL ROI | ANNUALIZED ROI |
| 2003 | 22.85% | 22.9% |
| 2004 | 10.30% | 16.4% |
| 2005 | 9.58% | 14.1% |
| 2006 | 11.44% | 13.4% |
| 2007 | 15.89% | 13.9% |
| 2008 | -24.05% | 6.5% |
| 2009 | 24.58% | 8.9% |
| 2010 | 4.10% | 8.3% |
| 2011 | 1.30% | 7.5% |
| 2012 | 11.00% | 7.8% |
| 2013 | 15.27% | 8.5% |
| 2014 | 5.00% | 8.2% |
| 2015 | 5.70% | 8.0% |
| 2016 | 5.50% | 7.8% |
| 2017 | 15.41% | 8.3% |
| 2018 | 4.33% | 8.1% |
| 2019 | 8.46% | 8.1% |
| 2020 | 16.91% | 8.6% |
| 2021 | 21.26% | 9.2% |
| 2022 | -18.61% | 7.6% |
| 2023 | 14.90% | 7.9% |
| 2024 | 22.80% | 8.6% |
| 2025 | 13.19% | 8.8% |
| 2026 | 13.01% | 8.93% |
Acting on this advice would have been a losing idea.
I’m glad I didn’t listen to those people telling me five or ten years ago that the market had been doing so well that it would level off. They said returns in the future would be “below average” for a long time. There is one thing I have learned about predictions regarding stock market returns. The predictor has a 50% chance of being right! Stocks and bonds will either go up or down during the predictor’s time frame. I make only one prediction about the market. The market WILL go both up and down!
If I had listened to people like that and bailed, I’d be a market timer. I am not a market timer. I don’t move in and out of the market based on hunches or a financial planner’s advice. I don’t move in and out of the market based on my hunches. I stay the course. Please reread the last sentence. I stay the course.
I had a friend who drove Cadillacs and owned his own company. He would tell me he could “feel” when the market was getting ready to take a dive. Luckily, I valued his friendship and bit my tongue. His logic sounded like so much horseshit. It did make me think about him a bit differently after he told me that in the future.
Pearl. I have never paid for investment advice.
I have never sought the advice of a financial planner to pick investments. I use people like that for estate planning, taxes, and other related tasks. I have never paid a financial planner a single penny for advice on which investments to choose or whether to be in or out of the market. My financial plan is super simple. I don’t buy individual stocks based on a tip or my research. I have other hobbies.
Pearl. This is how I did it. This is how I am doing it.
This is me. This is important. I have eleven mutual funds, most of them low-cost index funds. I don’t time the market; my stuff is broadly diversified. I am comfortable with this because I know enough about long-term investing to accept the expected outcome and live with the unexpected outcome.
A financial planner could be a good idea if someone doesn’t have a background in finance. I always tell people that when they get financial advice from anyone, they have to decide if that person stands to earn money by giving that advice. Quite often, they do.
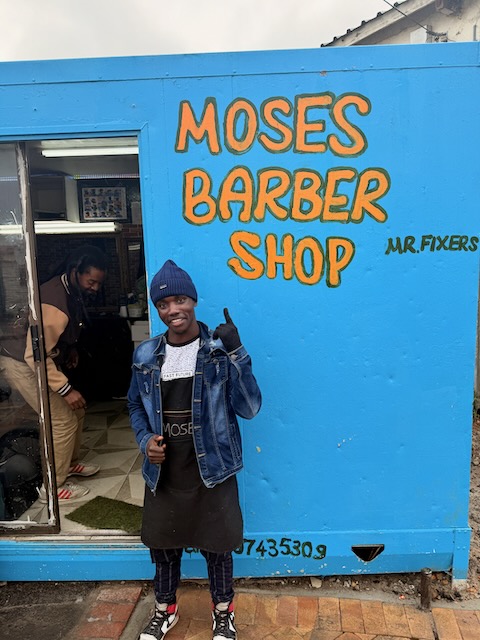
Pearl. Don’t do this.
I will take this adage to my grave. Don’t ask your barber if you need a haircut! Don’t ask anyone for advice if they stand to benefit from the advice they are giving you. Yes, I actually got my haircut at Moses Barber Shop in one of the townships of Cape Town, South Africa.
Pearl. Think you can beat the market?
You can’t. Just know that people struggle with this idea. It is EXTREMELY difficult to beat the market in the long run. If your financial planner tells you they can beat the market by enough to cover their fees and still give you a better-than-market return, you might ask them these questions. Can they guarantee that? Will they waive their fees if they DON’T beat the market? If you get a positive response to these questions, please share your financial planner’s phone number with me.
Pearl. Market timing is for suckers.
Some folks say the market has done well during my retirement years. I would agree. However, we did have a global financial crisis and a global pandemic. When those things happened, it would have been easy to step out of the market, potentially at the wrong time. Had I done that, I would have been a market-timer. A market timer has to be right twice. Once when they get out of the market and once when they get back in. I’m not smart enough to time the market once, let alone twice. Some people market time when they just KNOW what the future is going to be. Good luck with that.
In retirement, we’ve spent a lot of money and earned significant investment income. When I created that spreadsheet about our spending and potential retirement earnings expectations, I would have signed on the dotted line for an 8.93% annualized return over a long period, similar to what I’ve achieved over the past 24 years. That rate of return would have been good enough for me.
I work with arbitrage.
I told you that I have never worked for money since I retired. Some might disagree with that assessment. I have used various forms of arbitrage to create wealth. What is arbitrage? Is arbitrage magic?

Words to live by.
Warren Buffett says you will never get rich working during the day. You get rich while you sleep. I believe in that 100%.
While I was sleeping, our home has appreciated significantly since we moved in. Home appreciation is a form of arbitrage. I built the house for $2.4 million and now have an interest-only mortgage for $2.558 million on the property.
I asked ‘em for it…and they gave it to me.
Let’s stop here for just one moment. What bank in their right mind gives a guy who hasn’t earned a penny of work income in 24 years a mortgage for more than $2.5 million? Now, let’s continue.
What were these people thinking?
I was as shocked as anyone that the bank would give me a mortgage for more than two and a half million dollars when I had no work income or job. They did that just five years ago. Was I shocked? I was not so shocked as to not submit a loan application…so there’s that.
Do the math. I picked a good location. We live just 100 yards from the white water of the Pacific Ocean. Our realtor always said, “All money flows to the sea.” I believe he was right about that.
Pearl. Interest only. That’s enough to pay these people.
I like interest-only home loans. My current loan carries an interest rate of 2.25% over a 10-year term. I’m five years into that term.
Just think about this for a minute.
Let’s think about that. If I had wanted to own my home free and clear, the bank would have my $2,558,000 now. Here’s the fun part of that interest-only loan. I have the friggin’ two and a half million!
My house would still appreciate the same amount regardless of whether I had a mortgage. With that being the case, I decided to invest that $2.558 million in the hopes of earning a higher return than the 2.25% home interest rate the bank was charging me.
How is that going? I would say pretty well. For the last five years, my investment rates of return have been (-18.6%), 14.9%, 22.8%, 13.2%, and now 13.0%. With those returns that $2,558,000 has now grown to nearly $4 million. That’s a gain of well over a million dollars in just five years! If I had not gotten that interest only mortgage or if I had not gotten a mortgage at all I wouldn’t have that million dollars of investment earnings.
Should you really own your home free and clear?
I’m doing very well by investing the money rather than paying off my mortgage. The benefit comes from investing the amount of my home mortgage and NOT giving that money to the bank. I don’t want my money to be buried in the black hole of home equity, earning nothing. Folks, more than a million bucks is serious money!
During these first five years, I paid the bank nearly $300,000 in mortgage interest. The net gain of roughly $700,000 ($1,000,000+ minus $300,000) is a pretty nice piece of change for taking an interest-only loan and investing the proceeds the bank didn’t get to, to achieve a mortgage-free home. Given all of this data, do you still think it’s best not to have a mortgage on your home?
Let’s say that in the first five years of that home loan, my investments did not outperform the 2.25% interest rate on my mortgage. What then? I would still have control of more than $2.5 million to use as needed. I would also have that money in place when the market provided better, more expected long-term returns.
Oh, yeah…a couple more things. With my last refinance of the $2,558,000 loan, the bank gave me $300,000 in cash to spend as I liked. Yes, crazy! Well, it wasn’t exactly cash. They sent me a check! I cashed that check within an hour of receiving it!
I can take $30,000 a year from that money and do so for about 15 years, with investment growth, before that bucket of funds goes to zero. I can do a lot of traveling with 30 grand a year.
Finally, in five years, my mortgage loan (the IRS limits the mortgage interest deduction to just $1 million of the loan amount each year) has thrown off more than $100,000 in tax deductions. Those deductions have reduced my taxes (31% tax rate) by more than $30,000.
I’ve used the same principle with my car loans since 2019. Borrow at low rates and invest in the market at returns far above my car loan rates.
Pearl. How about some more arbitrage?
One last arbitrage item for me. I practice credit card arbitrage. Credit cards offer sign-up bonuses. They might give me 100,000 points if I spend something like $5,000 on their card in three months.
I don’t charge anything on the card that I wouldn’t have bought anyway. We pay our bill in full each month. Every 100,000 points I earn is worth about $3,000 in travel expense reduction to me. We have had 32 credit cards during the past two years. I have now discontinued seven of them because the arbitrage opportunity stopped for those cards.
And why do credit card issuers do this?
Why do credit card issuers seek new business this way? Because some people get a new card, charge lots of stuff, and don’t pay their bill in full each month! The credit card folks love people like that. I do too. If the credit card companies couldn’t count on those deadbeats, I couldn’t get those bonuses!
I charge everything humanly possible to charge on a credit card. Everything? I’m talking about federal and state income taxes and real estate taxes. I’m talking about insurance premiums and trips to McDonald’s, where my ice cream cone bill might be $1.99.
Pearl. Earn money in rebates that you would have spent cash on later.
I earn travel rebates that reduce my airfare and hotel expenses. As an example, if the best rate I can find on a Hyatt Hotel is $200/night, I use my credit card arbitrage earnings and points to bring that hotel expense to zero. In 2024, I earned $92,300 in pre-tax travel rewards. That’s serious money! I don’t have to spend those rewards in a single year. I don’t even have to spend these rewards on myself. I can give them to whoever I want.
Money is coming in from all directions.
As you can see, we don’t skimp on spending. My stock and bond portfolio is throwing off an annualized return of 8.93% over 24 years. My arbitrage with our home and car loans, along with credit card arbitrage, is earning huge amounts of money—more than $1 million in five years.
Arbitrage works best with low-interest loans. I’ve had low-interest loans for years and will have them on our house and car for many more. Yes, current interest rates are up. However, I’ve been sharing my low-interest loan strategies for years with anyone willing to listen. You snooze; you lose.

Pearl. Not my ideas.
I’m not that smart. I didn’t think of all of this on my own. But I am smart enough to see and run with someone else’s good idea!
I rarely have an original idea. However, I pride myself on taking other people’s ideas and applying them to my situation. William Bernstein inspired me to decide how to create a retirement portfolio of stocks and bonds. I am indebted to Mr. Bernstein. I bounce my ideas off my son and good friends.
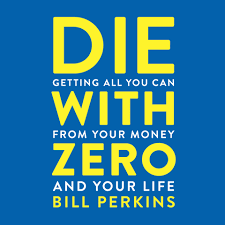
Pearl. This might be my favorite idea of all.
In golf they say a really good tip is one that you are still talking about six months later. I am still talking about Die with Zero years later!
I am indebted to a fellow by the name of Bill Perkins, who wrote a book called Die with Zero. I only discovered his book a few years ago. When I read it, I knew I had been practicing “Die with Zero” most of my life.
People roll their eyes when I tell them the book’s title, “Die with Zero.” The book doesn’t recommend trying to die with no money! The author advocates optimizing for personal enjoyment rather than for money. If anyone reading this thinks I am trying to optimize for money, they’ve missed the point. I am trying to optimize for personal enjoyment by managing money well.
Pearl. Your money is for creating memories.
Perkins recommends creating lasting memory dividends with your money. Nevertheless, some people don’t want to hear that. They want to keep their money in the bank or an investment account. Why? People don’t like to change. That’s on them.
I strongly believe in exploring new ideas. When a better idea comes along, I will switch in a heartbeat. I don’t practice that theory in marriage, though! Of course, I have never had to consider a better marital idea because none has ever come along. A better marital idea doesn’t exist for me! I needed to put that last part in just in case Carol reads this far.
The Die with Zero concept was not new to me, but the label was.
I have been using the principles of Die with Zero pretty much all my life. Long before I retired, our family traveled their butts off. I earned 500 frequent flyer airline tickets while I was working. 500! Just to be clear, I am not exaggerating. People who know me know I don’t exaggerate.
When the family traveled, I was often upgraded to first class. When that happened, I NEVER rode up front. We always had a way to get Carol or one of the kids into first class.
I have always spent a lot of money on houses, cars, and travel. I wanted to optimize for personal enjoyment and not for money. Money unspent isn’t worth much. Money held until you are too old to enjoy it isn’t worth much.
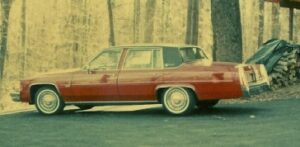
In 1980, I was 31. I bought a brand-new, fire-engine-red 1980 Cadillac Sedan DeVille. I was optimizing for personal enjoyment. Sadly, that Caddie was the worst car I ever bought! My boss drove a beat-up, little- bitty Honda hatchback. On many days, our two cars were parked right next to each other at work. That might not have been my most brilliant corporate political move…but he took it pretty well.
Carol and I have lived in our current house longer than we have in any other place. During my business career, we lived in Peoria, Illinois; Fairfield, Ohio; Phoenix, Arizona; Mission Viejo, California; Ridgefield, Connecticut; Inverness, Illinois; and Laguna Niguel, California. We are now in our second house in San Clemente, California.
Pearl. Stretch yourself on that house payment. You’ll be glad you did.
In each location, we stretched to get the biggest and best house we could afford. Why do that? We wanted to be comfortable. They say you gotta spend money to make money. They also say the cheap man pays the most. I love that last one. It’s so true.
Pearl. Location = appreciation.
Today, our home is worth nearly three times more than we paid for it. Location, location, location. When a relatively small number, $2.4 million, grows by nearly three times, you’ve got a much bigger number. You feel me, right?
Pearl. All I ever wanted from this was to be average.
There is nothing wrong with being average. When I retired, I wasn’t shooting for, or expecting, superior financial results with my low-cost stock and bond index mutual funds. I only wanted to be “average”. I just wanted to match the market. I figured the only way I could match the market was to be the market. After reading several investing books, I strongly believe that virtually no one beats the market.
We were lucky to spend much of our retirement in a low-interest-rate environment. As I recall, our construction loan was in the 3% range.
Did I tell you that it took 11 months to do the architectural planning for our house? It took 18 months to build the house. That’s 29 months. On the day we moved in to take advantage of our home loan terms, we didn’t have a front door. All we had was a massive piece of carpet covering the open space. Carol didn’t like that in a big way. All I could say was that I never tried to tell her how to manage her stuff. We got through it.
Sequence of returns.
Do you know what “sequence of returns”? If not, here’s a simple explanation.
Imagine two investors who each earn an annualized return of 8% over 25 years. One experiences steady 8% returns every year. The other loses 20% a year for the first five years, then earns much higher returns in the years that follow to achieve the same annualized return over the full 25 years.
If neither investor withdraws any money, they’ll end up with the same balance, assuming the same starting investment and costs. But retirement changes everything.
When you’re withdrawing money from your portfolio, the timing of your returns can be just as important as your average return. Poor early-retirement returns can force you to sell investments at depressed prices, leaving less money invested to benefit when the market recovers. Even if strong returns follow, you may never fully make up the difference.
That’s why sequence of returns matters so much in retirement planning. It’s not just about how much you earn over time; it’s also about when you earn it.
My son, J.J., often reminds me of this concept, and he’s exactly right.
Pearl. Refinance. Refinance. Refinance.
Refinancing your home is a slog. It’s not fun. I always say a refinance is never done…until it’s done. It’s more fun to play golf and travel than to refinance your mortgage. Nobody said doing smart financial things was going to be fun. But…when it’s all done, and you’re making money or reducing your expenses that optimizes for personal enjoyment…that IS fun.
I can’t tell you how many times we have refinanced our homes. I would say it’s been well more than ten times. Each time I refinanced at a lower interest rate or with a better loan term, I thought I couldn’t do better. I have refinanced a lot, and every time, I did better. I don’t think I’ll ever beat the home loan I have now. I hope I’m wrong.
More than ten years ago, I discovered interest-only loans. In retirement, I wouldn’t want to have any other type of home loan than an interest-only loan. Why in the world would I want a principal and interest loan?
Why would I move money from my retirement portfolio, earning 8.93% over the long haul, to pay off a loan charging me a much lower interest rate? I wouldn’t want to do that. However, if my home loan rate were equal to or higher than my net investment earning rate, I wouldn’t want to borrow.
Pearl. Borrow baby, borrow.
Here’s another opportunity to take what I am saying out of context. Please don’t do that.
Bottom line…I wouldn’t want to have my house fully paid for in retirement. I think that is a devastating financial strategy.
Some people will tell me they “sleep better” knowing their house is paid for. That is a euphemism for “I don’t want to have any risk whatsoever”.
Some people prefer annuities because the return is guaranteed. No risk. A guaranteed rate of return will always be lower, over the long run, than a market return. How is that?
The person/entity giving you the guarantee is earning a market return. How could they take their profit and still give you a market return when they are only making a market return? They couldn’t.
I “sleep better,” knowing that money that could have been sitting in my home equity earning exactly NOTHING is, in reality, gaining 8.93% on average each year. I sleep so soundly that I rarely get out of bed before 8 a.m. I know some folks have a full day’s worth of chores done by that time of day… but then I don’t do chores.
Pearl. The secret to a successful financial result? Compounding.
My net worth has benefited from the most significant financial benefit anybody can have: compounding. I’ve earned 8.93% over a long investing period: 24 years. The longer I earn that rate of return, the bigger the investment account. That’s the benefit of compounding.

Pearl. Free! This is one of the most important concepts I am sharing today.
Whoa! This one is really important!
I consider most things that I buy nowadays to be FREE. Did Randy say free? Yes, he did. I don’t pay much attention to the price of anything, and price doesn’t influence my decision to buy something.
I’m not as young as I was when I retired in 2002, and I won’t live as long after 2026 as I have lived since 2002.
I will never spend all my money sitting in my investment accounts. I invested that money so that Carol, my family, and I could enjoy it. I told you a thousand words ago that money alone isn’t worth anything. Money is to be spent. Money is to be enjoyed. You can enjoy it, your family can enjoy it, or anyone else you choose to share your financial wealth with can enjoy it. If you or someone else doesn’t enjoy the money, then you were an idiot to bust your butt earning it in the first place.
Free? Randy, please explain further.
I told you that I consider the stuff I buy today to be free. If I don’t spend my retirement money, it will be sitting over at Vanguard when they start dumping dirt on my casket. How about an example of “free”?
Most people have some money saved in retirement. I’m going to say that money can be divided into two buckets. The first bucket of money is reserved for your living expenses until you die. Your living expenses include housing, medical expenses, food, utilities, insurance, taxes, etc.
Pearl. Please…take the time to understand this point.
Importantly, the second bucket contains your remaining retirement funds, which you will, in all likelihood, never spend. What good is money you will never spend?
This is money that is BEYOND what you need to cover ALL of your future living expenses.
I believe I can afford to take some of the money from that second bucket and SPEND IT NOW! I don’t need money from bucket #2 to live on because my “live on” money comes from bucket #1.
Carol and I are going to New York City in December. We do that once or twice every year. We will be staying in a suite in New York City. We will dine at the best restaurants and see the best Broadway shows. All of this stuff is free! The money comes from bucket #2. Remember, bucket #2 is holding the money I will never spend! If I don’t spend some or even all of the funds from bucket #2, then I worked to earn that money, save that money, and invest that money…for nothing!
How about another example? You’ve got the time, right? Let’s say you have $2,500, $25,000, or $250,000 in your bucket #2 of retirement investments that you NEVER expect to spend. Where will that money go when you die? To whoever is a beneficiary of your will. When will you die? You don’t know.
Now, let’s say you don’t die for one year to fifty years. Why wait to spend the amounts of money listed above that you NEVER expect to spend? I recommend you spend that money on yourself or your heirs NOW. They’ll likely enjoy spending that $2,500, $25,000, or $250,000 now more than when you die in X amount of years.
If you spend some or all of that bucket #2 money now, the stuff you buy will be FREE!! It didn’t cost you a thing. The money you spend now with this strategy is money you were never going to spend anyway. This is a new concept to some. Take a moment to understand the idea fully.
Pearl. What good is money if you don’t spend it?
If we don’t spend the money we’ve earned with a solid retirement financial plan, the money will be useless to us. Does it matter what a new iPhone costs or a basketball ticket, a hotel, or a restaurant?
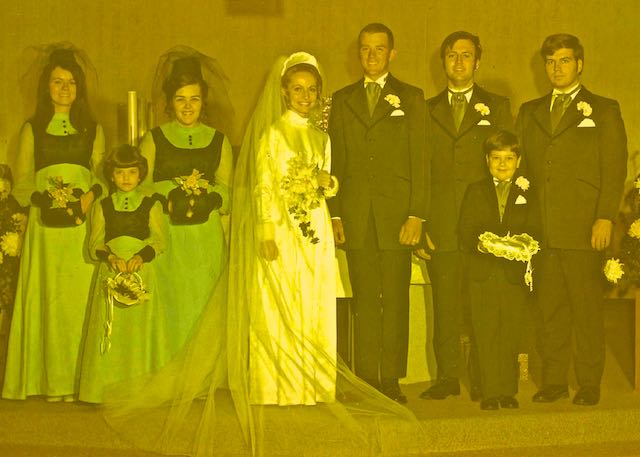
Carol and I were not always in this position. Our wedding costs were $500 in total. I was on leave from the Marine Corps. We paid for the entire thing. We took out a $200 bank loan to cover the remaining $ 300 of our wedding costs. This was the total cost of our wedding, including our rehearsal dinner and after-party.
We were practicing “Die with Zero” principles at age 23! We spent all our money, our entire net worth, plus $200, just for a big party! We optimized for personal enjoyment and created memory dividends. We knew those costs would be insignificant compared to the money we would have later in life.
When we were first married, we bought a king-size mattress and slept on the floor for the first year. We did that until we could afford the headboard and box springs we wanted. We got our China one dish at a time by making a $10 or maybe a $25 deposit into a bank account. We still have that fine China today. It looks great.
Pearl. This entire message about having a plan and getting results. It is not a message about money.
I don’t want anyone to think my life is only about money. Today’s newsletter is a message about the results I have achieved from my retirement financial portfolio. This particular newsletter is meant to talk about money.
Money is a supporting character in life. I would much rather have money than not. Money can create comfort. Money can create freedom. I would much rather have a comfortable life that offers freedom. That’s the value of money.
A message for all ages.
If you are in your 20s or 30s, you might still consider this a missive from some old guy. If you are in that age range and think you might want to emulate my retirement lifestyle, which began in my 50s, then you need a plan now. You can take elements of my plan or any other plan, but you need a plan. You need to work on that plan daily. You can’t deviate. You can’t market time.
If you’re young and poor, you can still save 25 bucks a week for the rest of your life. If you do, you will have a healthy chunk of change to enjoy in retirement. Don’t think you can save $25/month? I could walk into your household tonight and find much more than what you waste every week. You can’t blame anybody else for not having a plan.
If you are in your 40s or 50s, I hope you’ve been working on a plan for a while. If you haven’t, you need to stop what you’re doing immediately, get a plan, and work that plan 24/7.
If you are in your 60s or older, I hope you’ve enjoyed reading what I have shared. You’re in your own boat now. Your boat might be much smaller than mine, or it might be much larger. Whatever boat you’re in, I hope you’re comfortable, making memories, and sailing in whatever direction you like.
Pearl. Money has a declining utility over time.
Regardless of age, older folks need to understand that money’s utility declines over time. Cash is less valuable to you when you are 80 than when you are 30. You can do much more with money at age thirty than you can later.
If you can’t use your money today and still have several years of life expectancy, consider giving money to others. They, in most cases, CAN use that money today. Then, at least, you will get the psychic value of seeing someone enjoy your money.
Kids!
We have three kids. Well, they aren’t kids anymore but we still call ’em kids. You probably do too. They are in their late 40s and early 50s now. We were a “pay for performance” family. If you performed, you got paid. We decided that paying for our children’s college education would be our financial contribution to them. I (and Carol!) paid 12 years of tuition for our three kids to attend UCLA. What did we get out of doing that? Lots of sweatshirts and T-shirts, and a profound admiration for our kids’ achievements.
Luckily for everyone, they each graduated in four years! Then we gave them all a lovely graduation gift and sent them off financially. They have all done well, and we are exceedingly proud of them.
Pearl. Everybody’s older. What is the next step?
Now we are older. The kids are older. Should we give them money now, or wait another 20 years (hopefully!) for them to get some of our money after we’re gone? They will all be approaching seventy, then. At that point, THEY will be too old to enjoy skiing as much as they could when they were forty. We’ve come up with an excellent mid-range solution.
We don’t have to GIVE them any money right now, but we will. However, we can tell them right now how much they will be GUARANTEED (second-to-die life insurance) to get when Carol and I take the final checkered flag. Then they can spend the money they were planning to need for retirement NOW, knowing that our gifts will replace that money.
These may be “out of the box” ideas for some. Don’t take what I’ve said out of context.
I cautioned at the beginning that I hope no one takes anything that I’ve said out of context to support a personal point of view.
I have been 100% honest with you. I believe I have been more candid on these topics than virtually any source you might have from family, friends, or news agencies. Everything I’ve shared is 100% accurate and truthful.
I hope you didn’t think I bragged. I did all of this, so I guess I am justified in telling you how it all came down.
Pearl. Why share? So someone might get the results I’ve gotten.
A good friend recommended I say, “I earned 13.0%. It was a good year,” and leave it at that. I don’t roll that way. I want to help people. I don’t expect compensation, maybe a thank you somewhere down the line.
Someone who reads this might use my ideas or modify them to make them their own. When they do, they’ll likely be able to optimize their lives for personal enjoyment. They’ll also likely create lasting memory dividends. Memories are much more valuable than having a lot of money in the bank and no memories.
I hope you don’t think I am a financial stud. I am not. I have more money today than when I retired because I wasn’t smart enough to spend it until now. Maybe I worked too long. I’m trying to improve in this area.
I got to this point by listening to other people. I followed the advice of William Bernstein. I kept practicing the principles Bill Perkins offered in Die with Zero.
Was I lucky? I don’t think so.
Carol and I have been lucky in several vital areas. At the same time, I’ve found that the better we prepare, the luckier we are. I’ve heard it said that it’s better to be lucky than good, and I want to be both. We had a plan. We worked the plan. The plan is working for us.
Thanks for reading.
That’s it. Thanks for tuning in to my 2026 version of my “Financial Plan of a Lifetime.” Please pass it along if you like. I know you’re busy. Maybe you’re thinking there’s a lot of good stuff in here. You’ll act on things when your life slows down. We all know what that means. My recommendation? Act now.
Pearl. Predictions for the future.
One last thing. What is my projection for the future of stocks and bonds?
I have no frigging idea. That’s why I am not a market-timer.
You would have to think the market is ready for a pause since it’s been doing so well. That’s what people said five and ten years ago.
The market goes up, and the market goes down. That’s why I only look at market results every month or two.
I hope I haven’t made my “Financial Plan of a Lifetime” sound as if it’s easy to pull off. It’s not. But with the right plan, as I have, the odds will be dramatically in your favor.
Then, when the market does do well, you just need to know how to enjoy the rewards your good planning gave you.
I know this about the stock and bond markets: The markets will go up and down in the future. I don’t know when they will go up or down. I don’t want to be out of the market when it goes up. That would be stupid, painful, and financially hurtful.
See ya next year on this subject.
Randy said all of this. Yes, that’s my Swedish haircut! I don’t do chores. I got a good wife. She don’t eat much, and she don’t spend much money…but she does do chores. We enjoy living in our modest seaside cottage and traveling the world.
Yes, Randy said all of this…and Carol agrees, or at least nods her head!